7 min read
What Moved Last Week
The Federal Reserve raised rates by 25 basis points on September 16 to a target range of 3.75% to 4.00%, its first increase in three years. Equities took it calmly: the S&P 500 closed Friday at 7,650.50, up 0.17%. Treasury yields pushed toward 5% and the dollar firmed broadly, which did the week’s damage in FX.
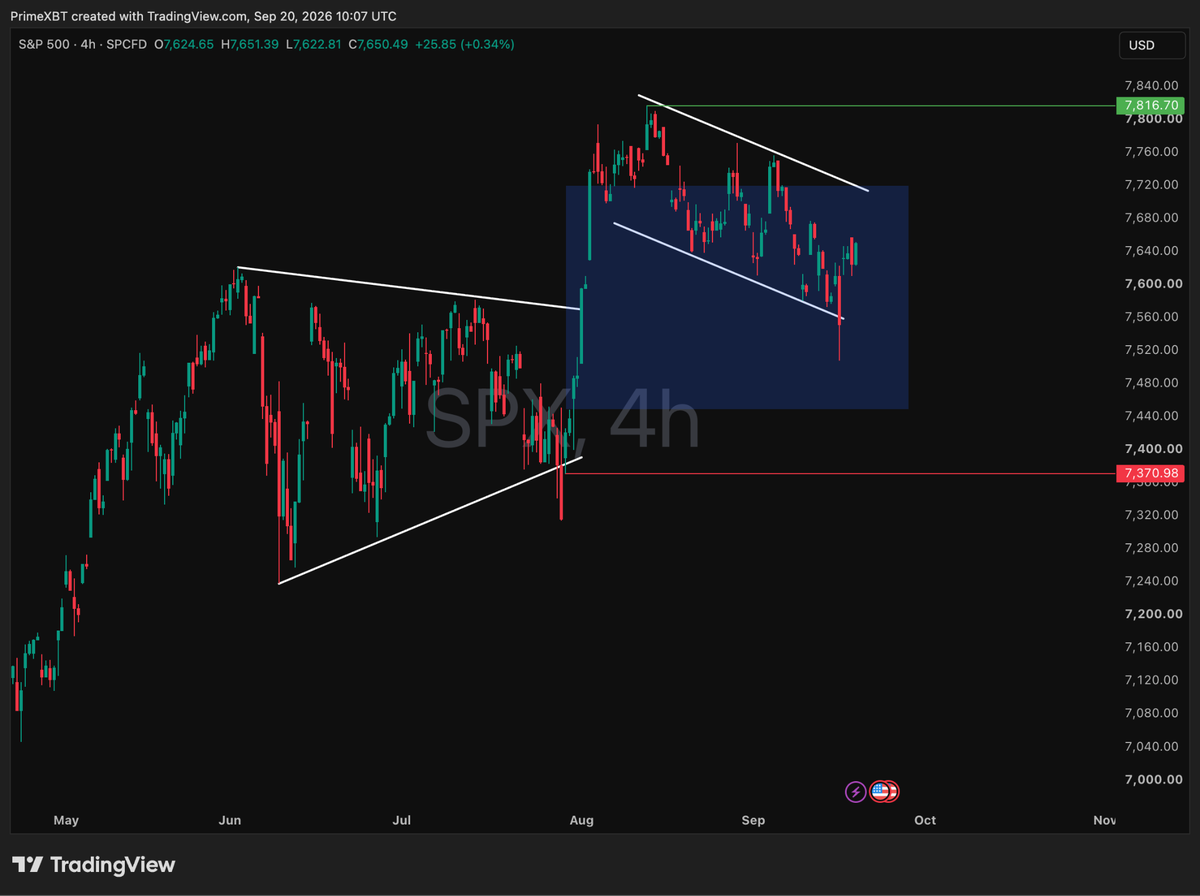
The index is still inside the descending channel that has framed price since the August high at 7,816.70. Buyers defended the lower boundary near 7,530 and reclaimed it within a session, which suggests liquidity below was taken rather than given away. The range holds while it does; a close back under it would put 7,370.98 back into the conversation.
Oil
Crude spent the week digesting a supply scare. Damage to Saudi Arabia’s East-West pipeline suspended export hub loadings, then Riyadh rerouted barrels through Oman and the premium drained away. Brent settled near $103, down roughly 1.4% on the week and the first weekly loss in three. The offsetting risk remains: four commodity vessels cleared the Strait of Hormuz on Thursday against a typical sixteen.
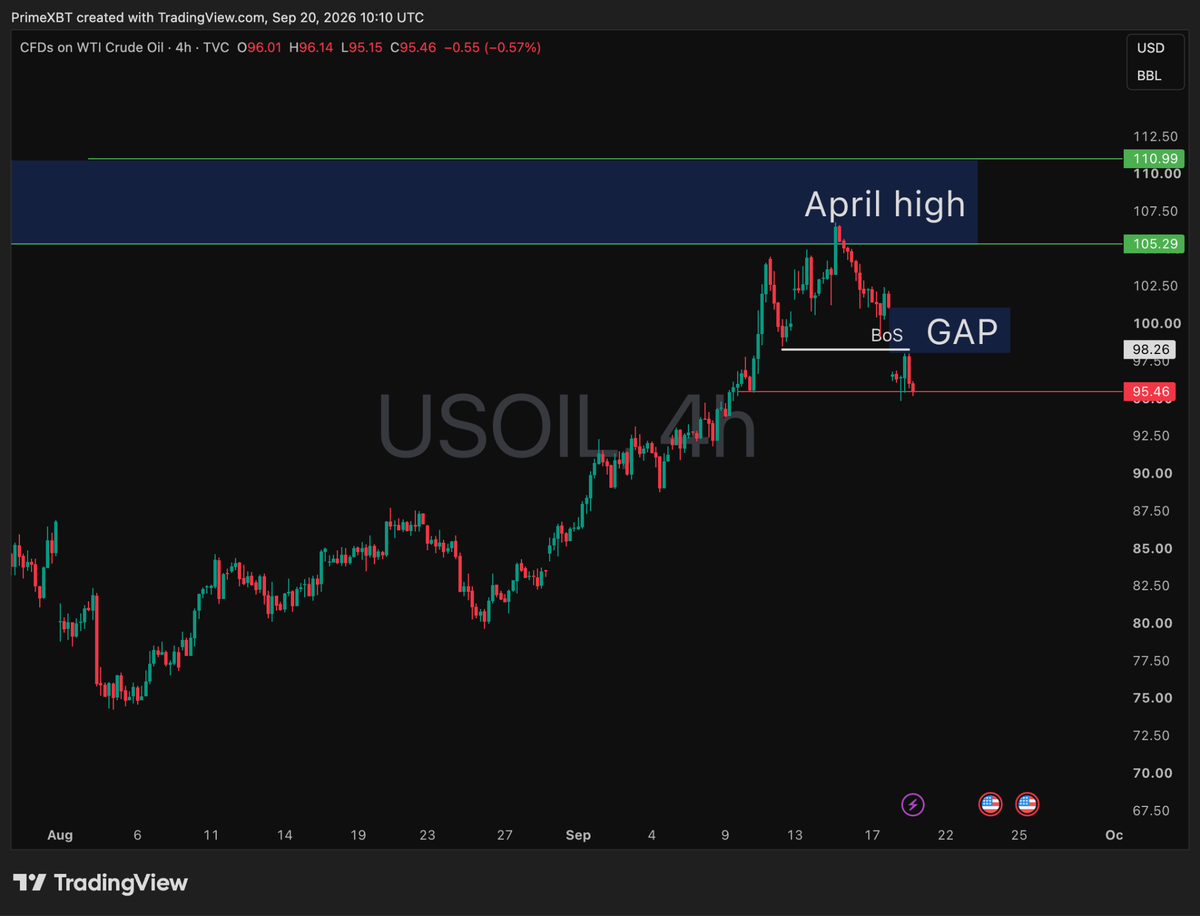
The push into the April high zone between 105.29 and 110.99 was rejected sharply, and the sell-off broke structure under the 98 shelf. That break left an unfilled gap just below 100. Price is sitting on 95.46. If the gap caps the bounce, the 90 handle is next below; a clean reclaim would undo the bearish break instead.
RBA Gov Bullock Speaks (Tuesday)
Bullock appears on Tuesday, days before the Monetary Policy Board meets on September 28 and 29. Her testimony on September 18 did most of the work already: she said the trade-off has got worse and that Middle East supply shocks are much harder to look through. Trimmed mean inflation ran at 3.6% year over year in July, above the 2% to 3% band. The cash rate sits at 4.35%, and pricing for a September increase firmed from roughly 70% before the hearing to about 95% after it. Tuesday matters mainly for whether she walks any of that back.
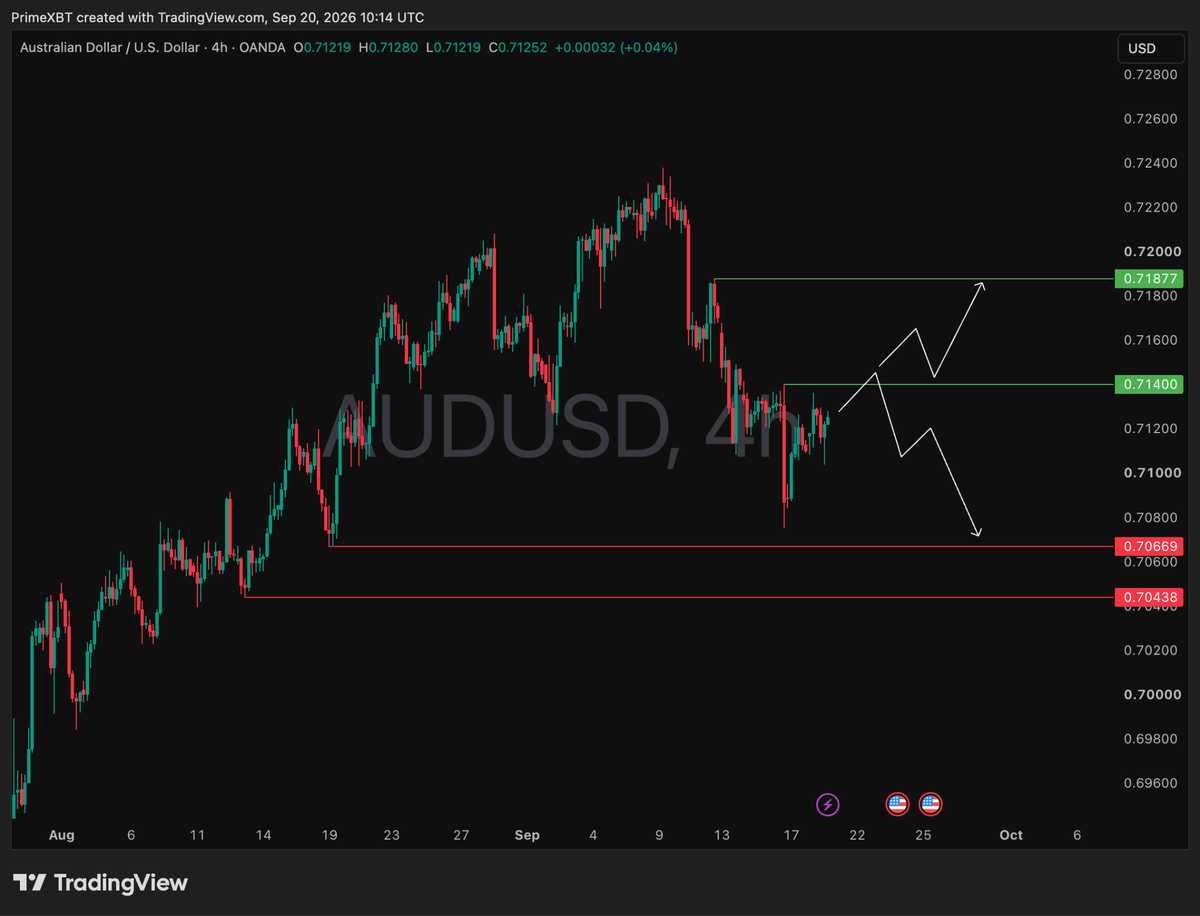
AUD/USD trades at 0.71252 after fading from the 0.71877 high. The sequence is lower, and a retracement into the 0.71400 shelf ahead of continuation is the cleaner structure to work with. The red levels at 0.70669 and 0.70438 are the first references below.
Flash Manufacturing PMI (Wednesday)
Wednesday brings the September flash PMIs across the euro area, the UK and the US, with Germany carrying the most weight. German manufacturing printed 54.3 in August, its strongest since May 2022, and consensus has the Q3 pace near 54.0. The euro area composite enters the month at 52.0. The detail worth reading is not the headline but the input and output price components, where higher energy costs would show up first.
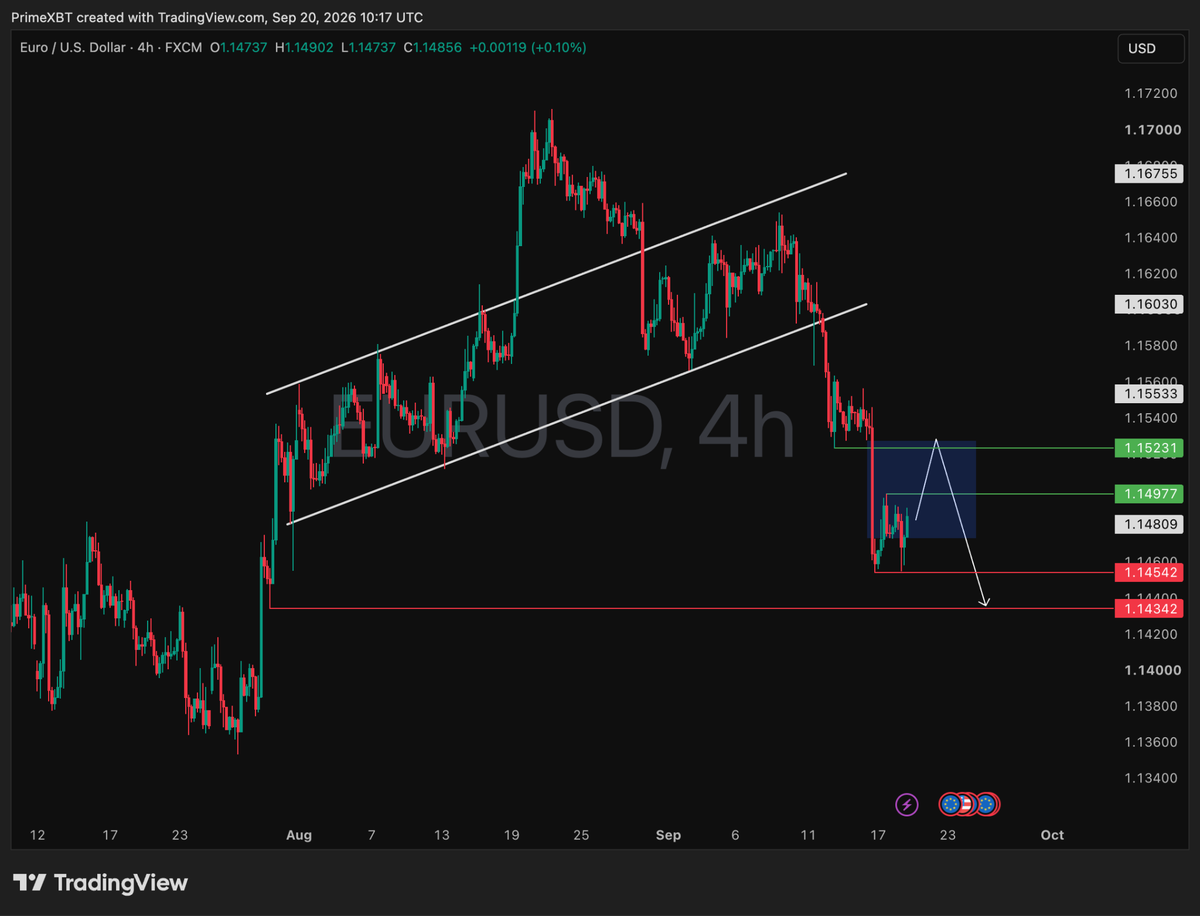
EUR/USD lost the rising channel that held since early August and trades at 1.14856. The downtrend stays valid while price remains under the broken lower boundary. The green levels at 1.14977 and 1.15231 mark the retracement zone where sellers have been active, and a reversal there on the lower timeframes is where the structure lines up. The red band at 1.14542 and 1.14342 sits below.
Australia Unemployment Rate (Thursday)
Thursday’s labour force report lands four days before the RBA meets. Consensus is 4.5% unemployment, unchanged from July and already the highest of the post-COVID period, with employment expected to rebound by about 20,000 after the 15,800 fall the month before. A soft print gives the case for waiting something to stand on; a firm one removes the last obstacle. The release lands in the Sydney morning, when most European desks are asleep, so anyone not watching live is better served trimming Australian dollar exposure and tightening stops beforehand.
SNB Policy Rate (Thursday)
The SNB has held its policy rate at 0% and no change is expected. Swiss inflation accelerated to 0.8% year over year in August from 0.4% in July, the fastest since September 2024, though core held at 0.4% and the print stayed inside the 0% to 2% band. The tradeable detail is the intervention language: in June the Bank flagged an increased willingness to intervene against rapid and excessive franc appreciation, and whether that sentence survives matters more than the rate. Switzerland is also the reminder of how quickly a stable currency stops being one, since the 2015 removal of the euro floor moved the franc by double digits in minutes.
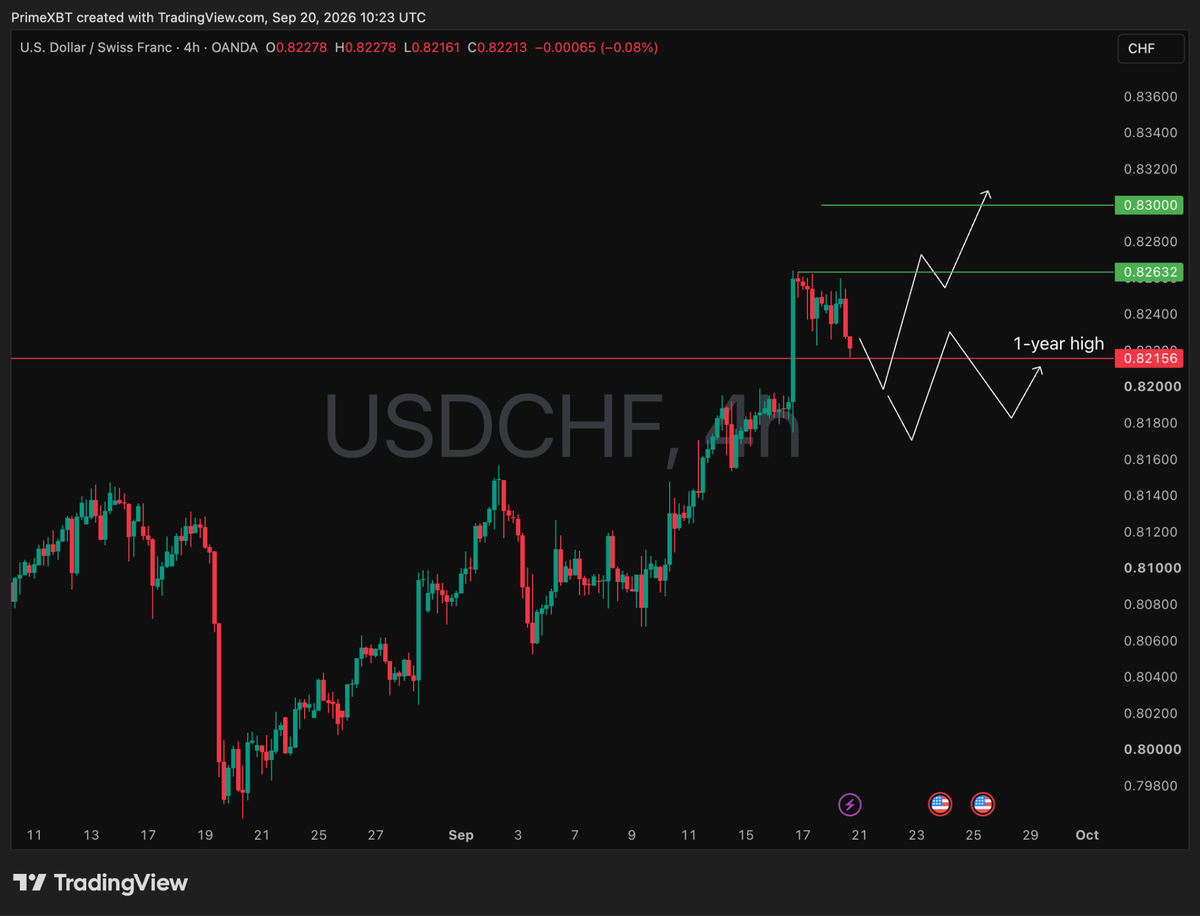
USD/CHF pushed through its one-year high at 0.82156 and is retesting it from above at 0.82213. A positive reaction off that level keeps the route toward 0.82632 and the round 0.83000 available. If the level gives way, the alternative is a longer correction measured in weeks rather than sessions.
BOE Gov Bailey Speaks (Friday)
Bailey speaks on Friday, eight days after the Bank held Bank Rate at 3.75% in a 6-3 vote, with three members pushing for 4.00%. UK inflation hit a five-month high of 3.1%, and the minutes warned inflation is likely to rise further over coming quarters. With that dissent on the record, the market will read Friday for whether the Governor leans toward the minority. If he restates the September line and stops there, the speech is background noise; if he engages with the dissenters’ case, December pricing moves with him.
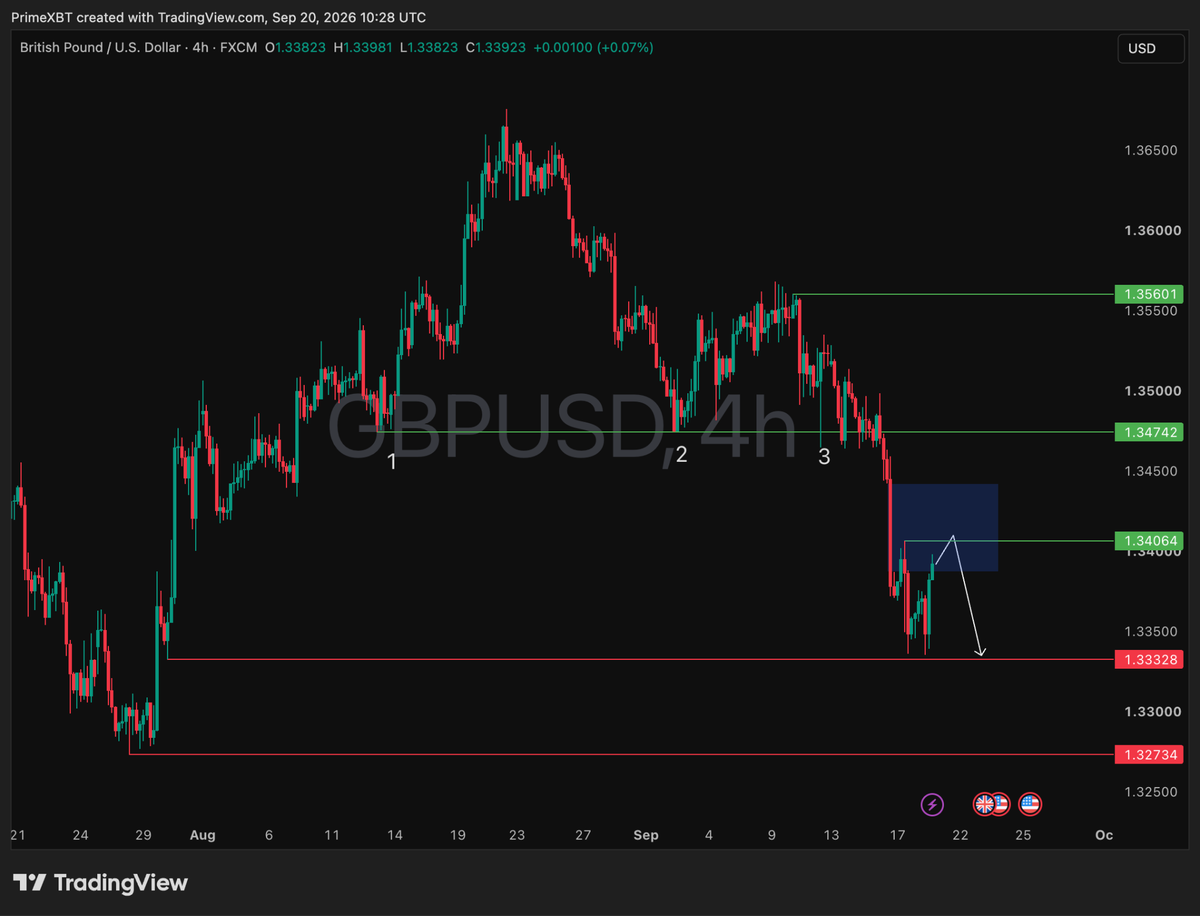
Sterling had a poor week, with GBP/USD falling to 1.3376 on Friday, down 0.59% and testing five-week lows, driven by a 0.28 point narrowing in the two-year yield spread rather than anything domestic. The chart closes at 1.33923. The 1.34742 shelf has capped price on three separate approaches, and 1.34064 is the nearer green level above. Below, a double bottom has formed at 1.33328 with stops resting under it, and 1.32734 is the next red reference.
Bottom line
This is not a heavy week for data. Four of the six calendar items are people talking rather than numbers printing, and the two real releases both arrive with consensus unchanged. That leaves tone and positioning doing the work. Autumn is also when volatility usually returns, so a thin calendar is not the same thing as a quiet tape.
Trading involves risk.
Author



 Risk Disclaimer
The content provided here is for informational purposes only. It is not intended as personal investment advice and does not constitute a solicitation or invitation to engage in any financial transactions, investments, or related activities. Past performance is not a reliable indicator of future results.
The financial products offered by the Company are complex and come with a high risk of losing money rapidly due to leverage. These products may not be suitable for all investors. Before engaging, you should consider whether you understand how these leveraged products work and whether you can afford the high risk of losing your money.
The Company does not accept clients from the Restricted Jurisdictions as indicated in our website/ T&C. Some services or products may not be available in your jurisdiction.
The applicable legal entity and its respective products and services depend on the client’s country of residence and the entity with which the client has established a contractual relationship during registration.