6 min read
What moved last week
Stocks ended the week higher even as bonds sold off. The S&P 500 closed Friday at 7,743.41, with AI and chip names leading. The 10-year Treasury yield touched 5.225%, its highest since 2007, after strong PMI data, a weak five-year auction and Fed officials signalling another hike. The Fed already lifted rates to 3.75%-4.00% on September 16.
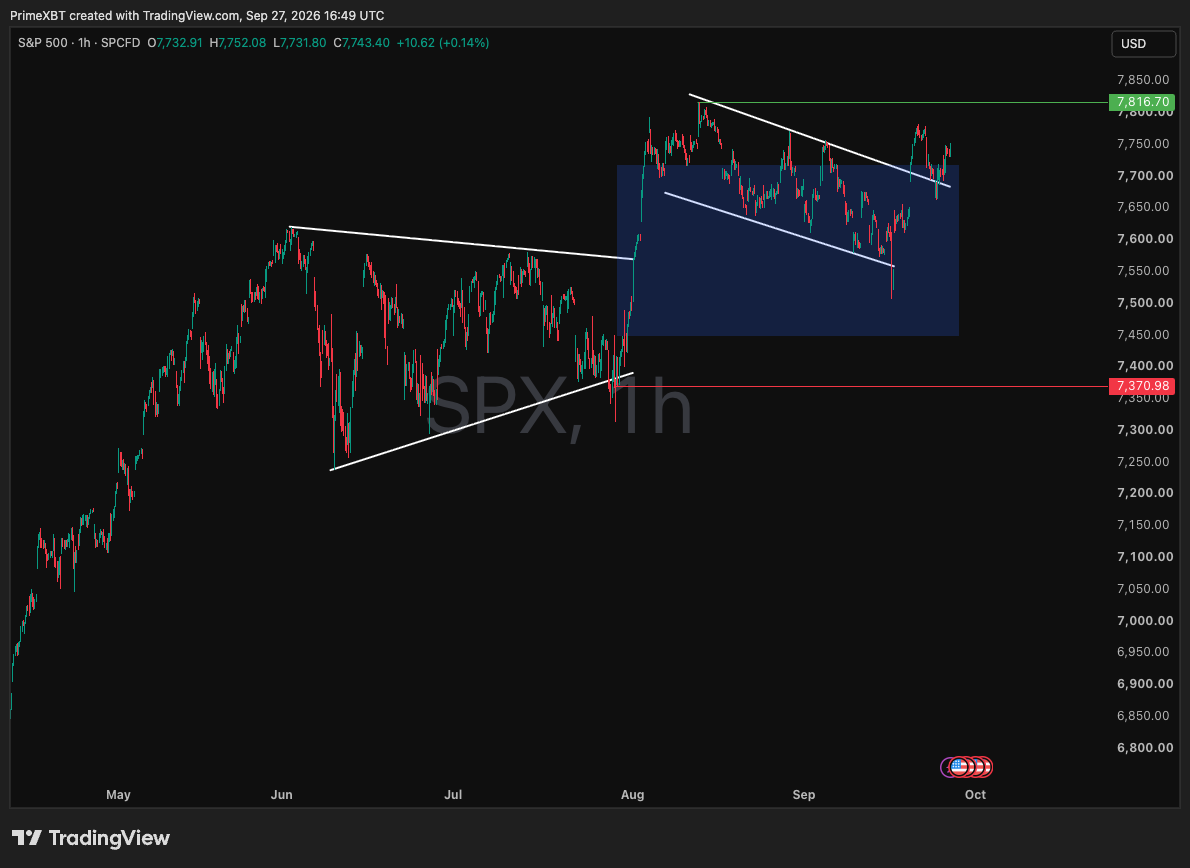
On the hourly chart, the S&P 500 broke out of the descending channel we tracked for two weeks and retested it from above near 7,700. If the retest holds, the next reference is the all-time high at 7,816.70, less than 1% away. A return below 7,700 would invalidate the breakout and open the path toward 7,450-7,550.
US 10-year yield at a 19-year high
The 10-year yield peaked at 5.228%, a level last seen in 2007, on the eve of the global financial crisis. It is the benchmark for mortgages, corporate credit and equity valuations. A sustained break above 5.228% would tighten financial conditions further without any action from the Fed.
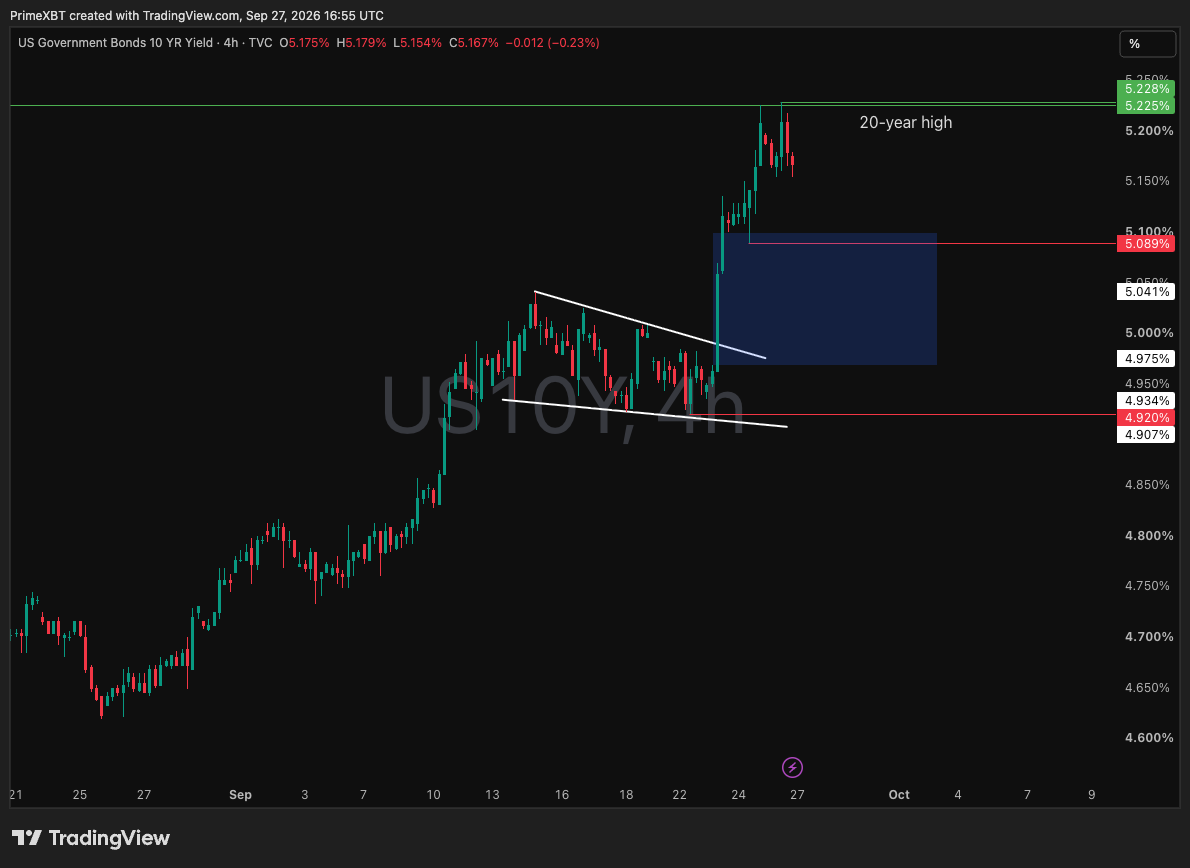
The yield broke out of a falling wedge on September 23 and left an imbalance between 4.975% and 5.10%. A pullback toward 5.089% and 5.041% would read as a healthy correction and ease pressure on risk assets. A push through 5.228% would signal the repricing is not finished, with higher risk-free returns competing directly with equities.
Oil gives back its war premium
WTI settled at $92.41 on Friday after the US and Iran resumed direct talks, their first since June, on a phased deal to reopen the Strait of Hormuz. Brent held above $104 on Houthi attacks on Saudi infrastructure.
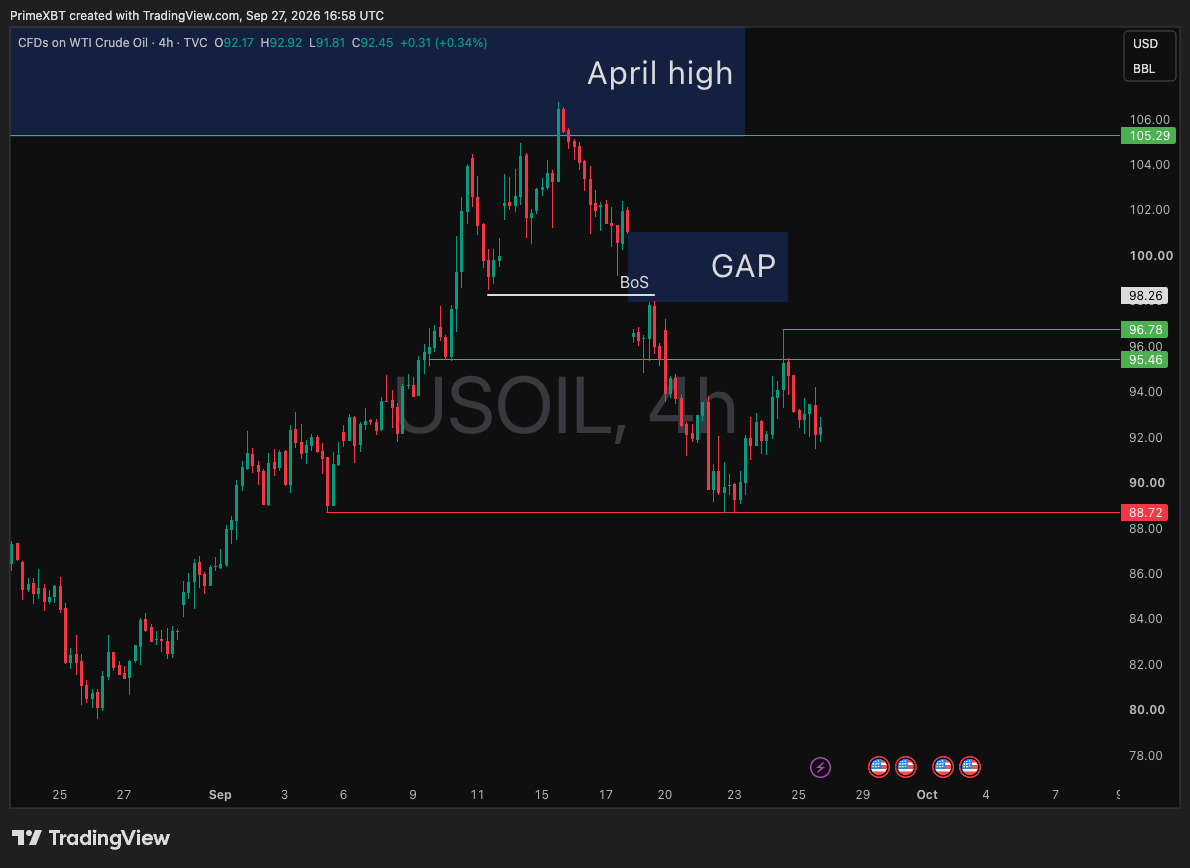
WTI crude reached the 88.72 support we flagged a week earlier, bounced into 95.46-96.78 and turned lower. Price trades near 92.45, and the structure stays bearish below the 98.26 break of structure and the gap above it. A 4-hour close below 88.72 would remove the last support visible since early September.
RBA cash rate and CPI (Tuesday and Wednesday)
The RBA decides on Tuesday at 04:30 GMT. Most economists expect a 25 bp hike from 4.35% to 4.60%, the highest since 2011, after the July trimmed mean held at 3.6%, above the 2-3% target. August CPI follows Wednesday at 01:30 GMT. With a hike largely priced, a hold would be the bigger surprise for the Australian dollar.
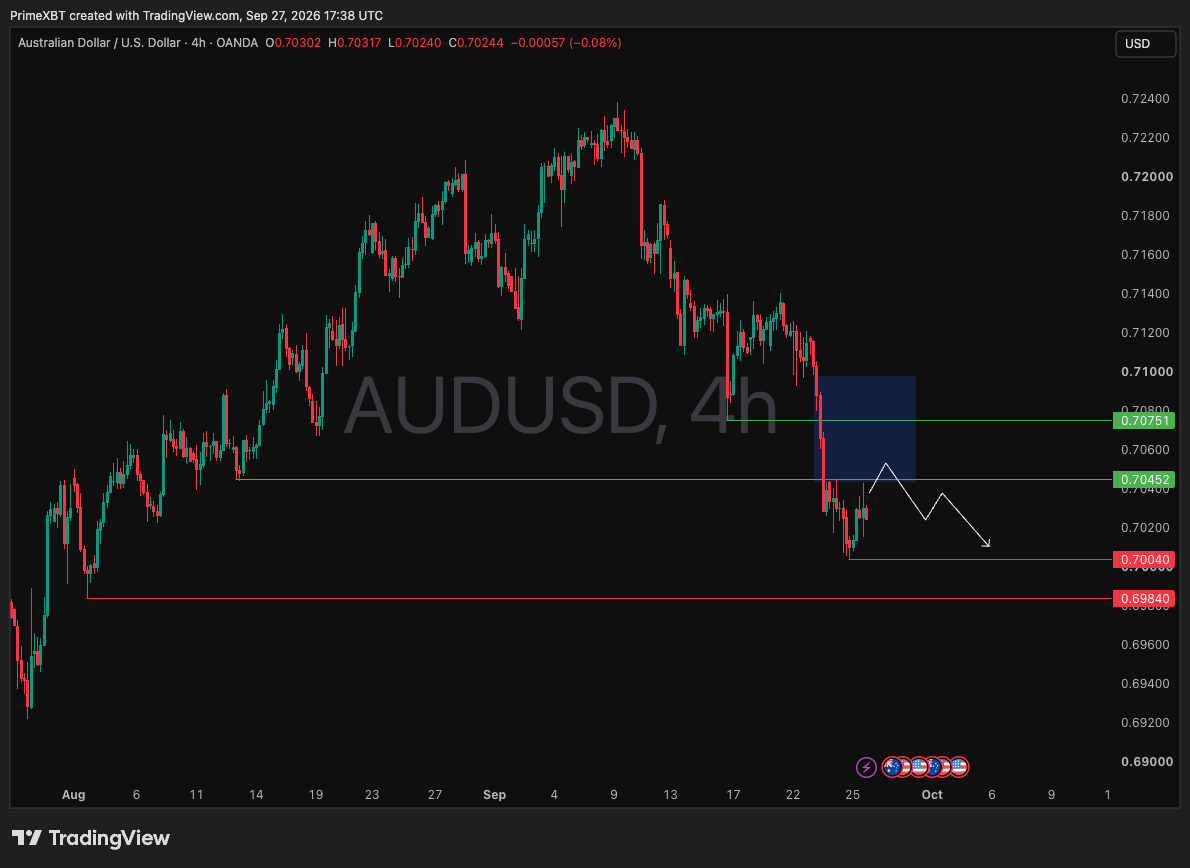
AUD/USD fell from above 0.7230 to 0.7004 despite the hawkish repricing, a sign that dollar strength dominates. The drop left an imbalance between 0.7045 and 0.7100, and a retest is the logical next step. If lower timeframes turn down from there, continuation opens the path toward 0.7000 and 0.6984.
US final GDP and PCE (Wednesday)
Wednesday at 12:30 GMT brings the third estimate of Q2 GDP, previously 1.5% annualized, together with August PCE. July core PCE ran at 3.3% year over year. PCE is the market-moving number: Warsh called inflation “too high” in September, and a hot print would harden the case for another hike.
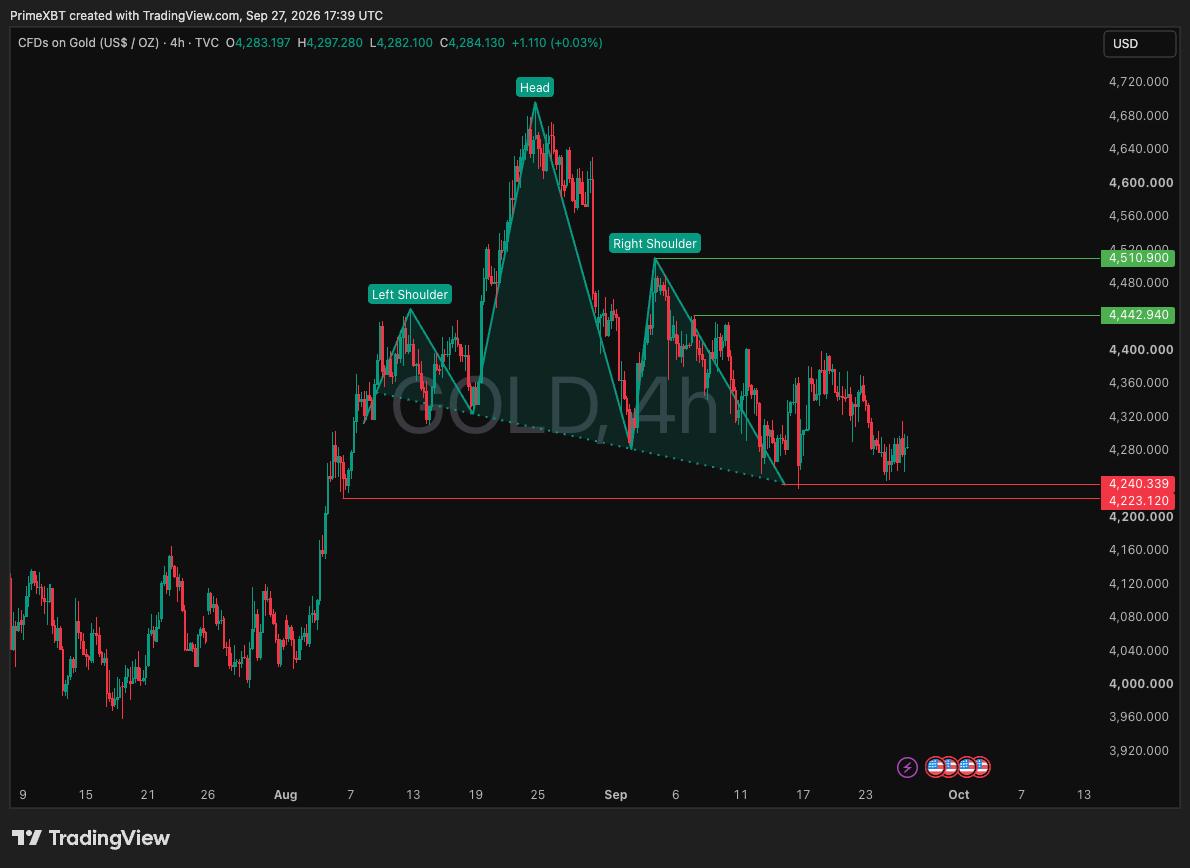
Gold is completing a head and shoulders top, with the right shoulder at 4,510.90 and price at 4,284 just above the 4,223-4,240 neckline zone. A move below 4,240 would confirm the breakdown and open the path toward 4,200 and then 4,100. A recovery above 4,442.94 would weaken the pattern.
Swiss CPI (Thursday)
[CHECK NUMBERS FOR THIS ABSTRACT]
Swiss CPI is due Thursday at 06:30 GMT. August rose 0.4% on the month and 0.8% on the year, the fastest annual pace since August 2024, driven by petrol and a weaker franc. Consensus for September is 0.0% m/m. The SNB held at 0% on September 24, so the print matters more for the franc than for policy.
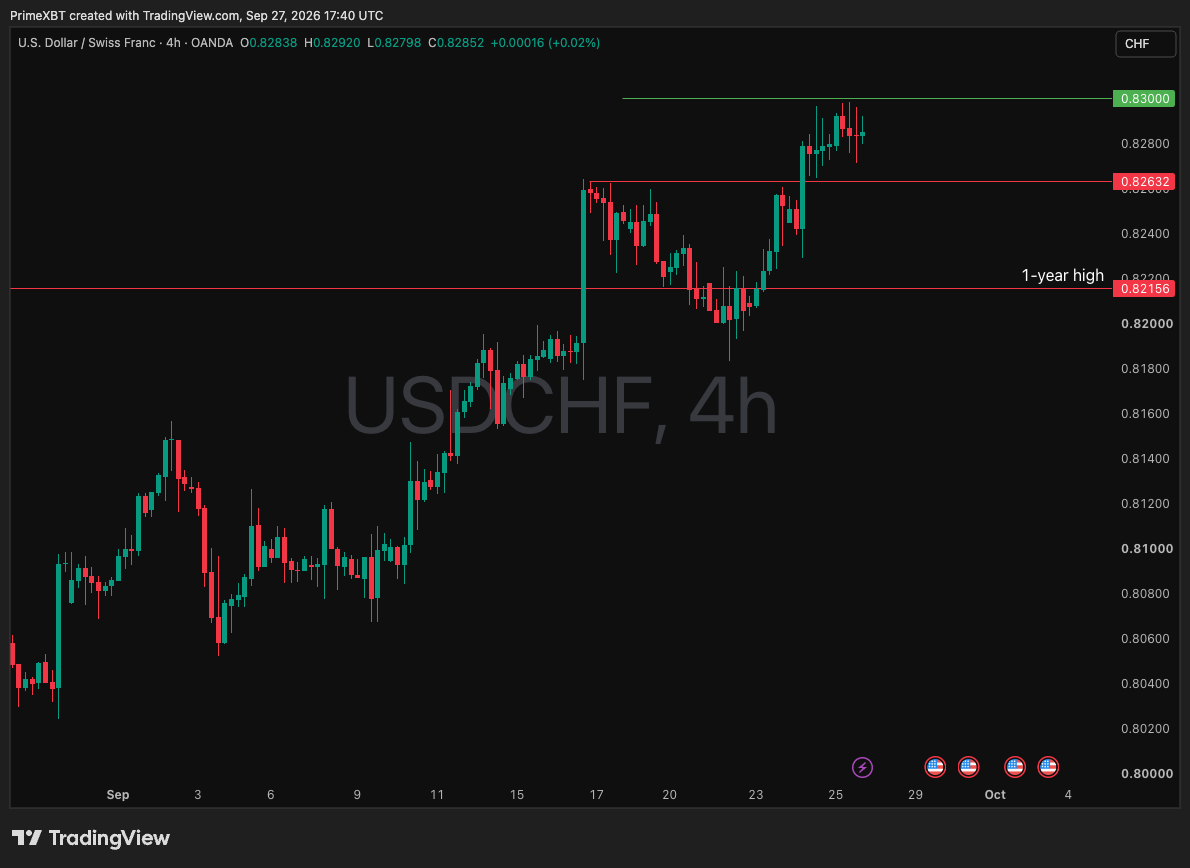
USD/CHF broke its one-year high at 0.82156, retested it and pushed to 0.8300. A 4-hour close above 0.8300 would confirm the next leg higher. Failure there leaves room for a pullback toward 0.82632 and another retest of 0.82156.
US nonfarm payrolls (Friday)
September payrolls land Friday at 12:30 GMT. August added 162,000 jobs with unemployment at 4.1%. Consensus sits around 90,000-100,000. A strong print on top of hot PCE would strengthen hike expectations and push yields back toward their highs; a miss would ease that pressure.
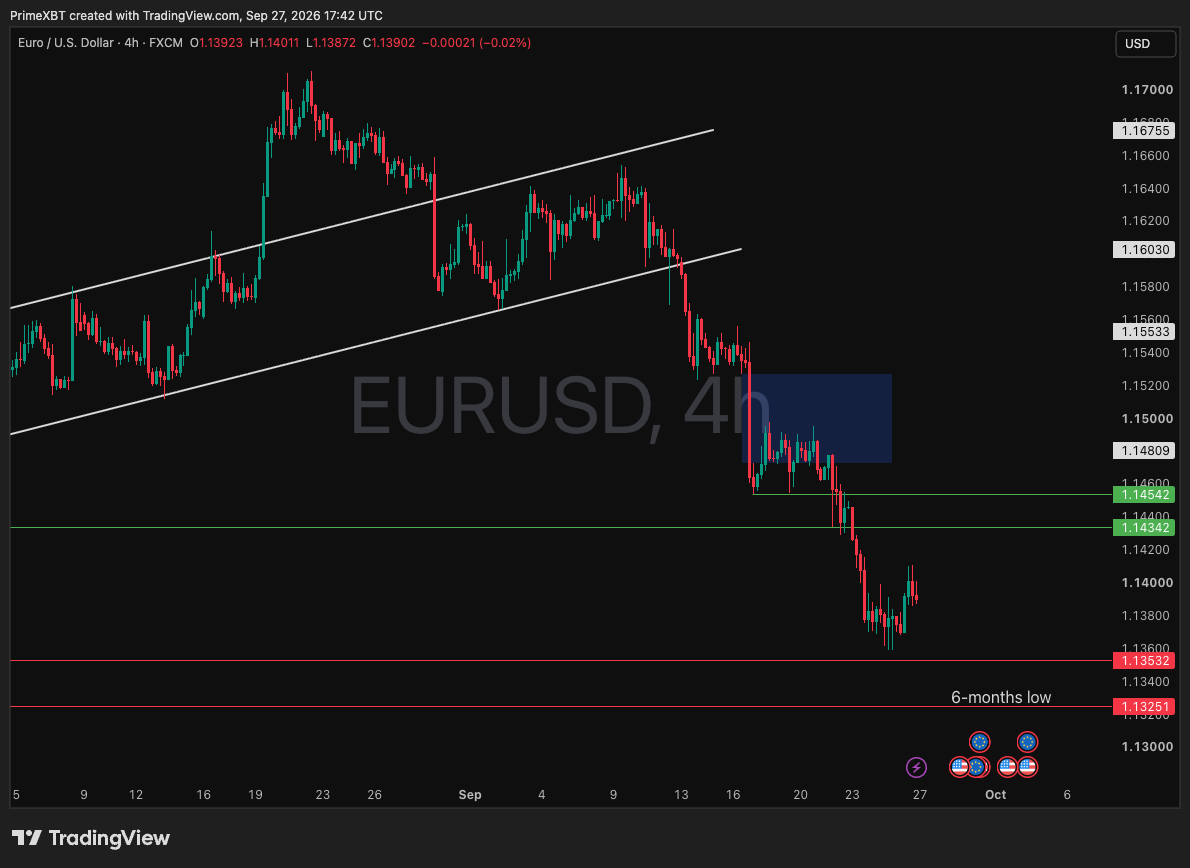
EUR/USD trades at 1.1390 after breaking below its rising channel in mid-September. Supports sit at 1.13532 and the six-month low at 1.13251, and a renewed climb in yields raises the odds of a break. Resistance stands at 1.14342 and 1.14542.
Bottom line
The week turns on how far yields can rise before risk assets react. The S&P 500 sits within 1% of its record while the 10-year holds near a 19-year high. A pullback in yields toward 5.04-5.09% would support the equity breakout and give gold and EUR/USD room to stabilize. A break above 5.228% would pressure all three and extend the dollar’s run.
Trading involves risk.
Author



 Risk Disclaimer
The content provided here is for informational purposes only. It is not intended as personal investment advice and does not constitute a solicitation or invitation to engage in any financial transactions, investments, or related activities. Past performance is not a reliable indicator of future results.
The financial products offered by the Company are complex and come with a high risk of losing money rapidly due to leverage. These products may not be suitable for all investors. Before engaging, you should consider whether you understand how these leveraged products work and whether you can afford the high risk of losing your money.
The Company does not accept clients from the Restricted Jurisdictions as indicated in our website/ T&C. Some services or products may not be available in your jurisdiction.
The applicable legal entity and its respective products and services depend on the client’s country of residence and the entity with which the client has established a contractual relationship during registration.